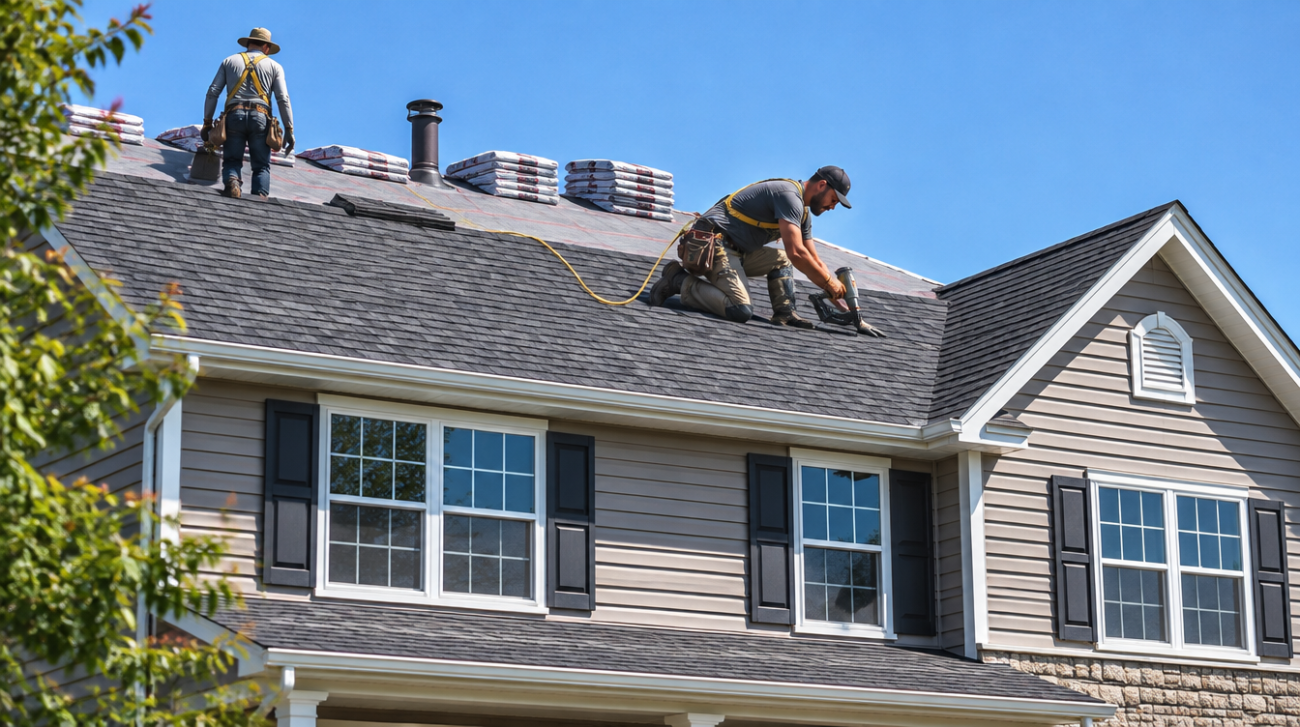
The cheapest way to finance a roof replacement is usually a home equity line of credit, followed by a personal loan from a credit union. But the first step costs nothing at all: check whether your homeowners insurance will pay. On a $12,000 roof, the gap between the best and worst financing choice is more than $5,000 in interest, so a few hours of comparison is worth real money.
Most roof financing guides list the options and stop there. This one puts them in the order you should check them, shows what each one costs on the same $12,000 roof, and flags the two traps that cost homeowners the most: actual cash value insurance and “no interest if paid in full” contractor deals.
Key takeaways
- Check your insurance first. Storm damage may be covered, but wear and tear almost never is.
- On a $12,000 roof over five years, a HELOC at 7.49% costs about $2,400 in interest. A credit card at 21.52% costs about $7,700.
- “No interest if paid in full” offers charge all the interest back to day one if you miss the deadline.
- Low income homeowners, especially seniors in rural areas, may qualify for repair grants or 1% loans.
- In Alabama, Louisiana and Kentucky, state grants of up to $10,000 help pay for storm resistant roofs.
- Get at least three written quotes before you choose a loan amount.
Step 1: Find out if insurance will pay for the roof
Homeowners insurance covers roof damage from sudden events such as wind, hail, fire or a falling tree. It usually does not cover a roof that simply wore out. Amica sums it up plainly: damage from age, neglect or wear and tear is usually not covered.
If you do have a covered claim, the type of coverage decides how much you get. With replacement cost value (RCV), the insurer pays to replace the roof at today’s prices, minus your deductible. With actual cash value (ACV), the payout is reduced for the roof’s age. The Texas Department of Insurance gives a clear example for a roof that costs $10,000 to replace:
| Roof age | ACV payout before deductible | You pay (before deductible) |
|---|---|---|
| 5 years | $8,500 | $1,500 |
| 10 years | $7,000 | $3,000 |
| 20 years | $4,000 | $6,000 |
Two practical tips. Many policies have a separate, higher wind and hail deductible, so check that number before you file. And under RCV, the insurer often pays the depreciated amount first and the rest once the work is done, so you may need short term money to bridge the gap.
Step 2: Make sure you need a full replacement
A repair is far cheaper when the roof is fairly young and the damage is limited. Fixr puts the average roof repair at $1,150, with most jobs between $400 and $1,900. If you are unsure, our guide on roof repair vs. roof replacement walks through age, damage extent and the signs that a patch will not last.
Step 3: Get a real number before you borrow
National averages give you a starting point. This Old House puts the average replacement for a 2,600 square foot house at about $9,933, with a range of $7,635 to $25,284 depending on stories, location and material. Fixr puts asphalt shingle replacement at an average of $12,000. We use $12,000 in the examples below.
Prices are also climbing. Insurance claim data from Verisk shows the average residential roof replacement reached $17,631 in 2025, about 33% above the 2021 to 2024 average. Claim roofs tend to be larger, storm damaged jobs, so treat that figure as the high end, and expect quotes to rise if you wait.
Your own number matters more than any average. Get at least three written quotes that list materials, tear off, decking repairs and permits. Borrow for the quote you accept plus a small cushion for hidden deck damage, and no more.
Step 4: Compare financing options by total cost
Here is what the same $12,000 roof costs with each common option. We used national average rates and standard amortization. Your rate will depend on your credit, income and equity.
| Option | Rate used | Term | Monthly payment | Total interest |
|---|---|---|---|---|
| HELOC | 7.49% | 5 years | $240 | $2,424 |
| HELOC | 7.49% | 10 years | $142 | $5,086 |
| Personal loan, 700 credit score | 14.88% | 5 years | $285 | $5,083 |
| Personal loan, 620 credit score | 19.31% | 5 years | $313 | $6,800 |
| Credit card | 21.52% | 5 years | $328 | $7,690 |
| Contractor 0% promo, paid on time | 0% | 12 months | $1,000 | $0 |
Calculations by USA Home Guide, fees excluded. Rates: Bankrate HELOC average as of November 4, 2026; Curinos personal loan averages by FICO score via Experian, August 2026; Federal Reserve bank credit card average via Finder, 2026.
Notice that a 10 year HELOC has the lowest payment but costs about as much interest as a five year personal loan. A longer term buys breathing room, and you pay for it.
Run your own numbers
Roof financing calculator
Enter your numbers to see the payment and total cost.
Tip: run each offer you get through the calculator. Try the HELOC rate, your credit union’s personal loan rate and the roofer’s plan, and compare the total cost line.
1. Home equity line of credit (HELOC)
A HELOC lets you borrow against your home’s equity and pay interest only on what you draw. The national average HELOC rate was 7.49% as of November 4, 2026, according to Bankrate. Most HELOCs have variable rates, so your payment can rise. Approval takes longer than a personal loan, often a few weeks, because the lender needs to value your home. Your house secures the debt, so missed payments put it at risk.
2. Home equity loan
A home equity loan is a lump sum at a fixed rate, which makes budgeting easy. It suits a roof well, because you know the full cost up front. Expect closing costs and an appraisal. For a deeper comparison, see our guide on HELOCs vs. home improvement loans.
3. Personal loan
A personal loan needs no equity and no appraisal, and many lenders fund within a few days. That speed matters when water is coming through the ceiling. The trade off is a higher rate, especially with fair or poor credit. Credit unions are often cheaper than online lenders. Watch for origination fees, which come out of the amount you receive.
4. Roofer financing
Many roofing companies offer payment plans through a lending partner. They are convenient, and some advertise 0% for 12 months. Read the wording closely. According to the CFPB, an offer that says “no interest if paid in full” is a deferred interest deal: if any balance is left at the end, interest going back to the date of purchase is added on top. On a $12,000 roof, that means paying $1,000 a month without fail. A true 0% offer, by contrast, only charges interest on what is left after the promo ends.
5. Credit card
A card is the fastest option and the most expensive one for a full roof. It can make sense for a small repair you can pay off within a few months, or to cover a deductible. For anything larger, compare a personal loan first.
6. Cash out refinance
A cash out refinance replaces your mortgage with a bigger one and gives you the difference. It only makes sense if the new mortgage rate is close to or below your current one. If you locked in a low rate years ago, refinancing a large balance to pay for a $12,000 roof will usually cost far more over time.
7. Government backed and low cost programs
If your credit is weak or your equity is thin, look at FHA Title I property improvement loans, which have no program minimum credit score. Our guide to a home improvement loan with bad credit covers Title I, credit unions and other low score options in detail.
Step 5: Check for grants and free help
A failing roof is a health and safety hazard, which is exactly what most repair grants cover. In rural areas, USDA Section 504 offers grants of up to $10,000 to very low income homeowners aged 62 or older, and 1% loans of up to $40,000, according to USDA Rural Development. Many cities and counties run their own emergency repair programs too. If you or a parent is over 60, start with our guide to home repair grants for seniors.
State grants for storm resistant roofs
In hurricane and hail country, several states pay homeowners to replace an old roof with one built to the FORTIFIED standard from the Insurance Institute for Business and Home Safety. If your roof needs replacing anyway, these grants can cover most of the job and lower your insurance bill afterward.
| State | Program | Grant | Good to know |
|---|---|---|---|
| Alabama | Strengthen Alabama Homes | Up to $10,000 | Owner occupied single family homes, no income limits, open by county on a rolling schedule |
| Louisiana | Louisiana Fortify Homes Program | Up to $10,000 | Lottery based; you pay the evaluation and any cost above the grant |
| Kentucky | Strengthen Kentucky Homes | Up to $10,000 | Statewide program planned to open in spring 2026; check current rounds |
Sources: Smart Home America funding list, Roofing Contractor and the Brookings Institution, 2026.
The savings can be real. A Louisiana Legislative Auditor review found that Fortify Homes grants cut insurance costs by a median of 22%. Other states, including South Carolina and Mississippi, have run similar programs, so check your state insurance department’s website for open rounds before you sign a roofing contract.
Mistakes that make a roof cost more
- Signing with a storm chaser. After big storms, out of town crews knock on doors and push you to sign on the spot. Use a licensed local roofer and check reviews.
- Letting a contractor arrange your loan without comparing. Get at least one quote from your bank or credit union to compare against.
- Choosing the lowest payment instead of the lowest total cost. Stretching to 10 years can double the interest.
- Waiting too long. A small leak can turn into rotten decking, mold and a much larger bill.
- Paying a large deposit up front. Tie payments to milestones, with the final payment after inspection.
Frequently asked questions
What is the best way to finance a new roof?
For most homeowners with equity, a HELOC or home equity loan has the lowest interest cost. Without equity, a personal loan from a credit union is usually the next best choice. Always check insurance and grants first.
Can I finance a roof with bad credit?
Yes, though choices are narrower and rates higher. Look at credit unions, FHA Title I loans, secured loans and local repair programs, and compare the total cost before accepting roofer financing.
Will homeowners insurance replace an old roof?
Not because of age alone. Insurance pays for damage from covered events such as wind, hail or fire. On older roofs, many policies pay actual cash value, which subtracts depreciation, so you may cover a large share yourself.
How long can you finance a roof?
Personal loans usually run two to seven years. Home equity loans and HELOCs can run 10 to 30 years. Roofer plans vary, often from 12 months to several years. Shorter terms cost less in total.
Is it better to pay cash for a roof?
If paying cash leaves you with a healthy emergency fund, cash is the cheapest option. If it would drain your savings, a low rate loan can be the safer choice, since a new emergency could force you into expensive debt later.
Sources
- Texas Department of Insurance, Replacement cost or actual cash value
- Amica, Does Home Insurance Cover Roof Replacement?
- Fixr, roof repair and asphalt shingle replacement cost data (2026)
- This Old House, roof replacement cost for a 2,600 square foot house (2026)
- Bankrate, HELOC rates (November 4, 2026)
- Experian, personal loan rates by credit score (Curinos data, August 2026)
- Finder, Federal Reserve consumer credit rates (2026)
- Consumer Financial Protection Bureau, special promotional financing offers
- USDA Rural Development, Single Family Housing Repair Loans and Grants
- Verisk, 2026 U.S. Roof Report
- Smart Home America, state FORTIFIED roof funding opportunities
- Brookings Institution, state incentives for storm resistant homes
- Roofing Contractor, Louisiana Fortify Homes lottery (May 2026)
Rates and costs were checked in November 2026 and change often. Confirm current terms with each lender before you apply. This article is general information, not financial advice.